Where pricing meets
capital modelling.
Shown here: VinkeRE Modelled Risks on a cat programme. The same core powers VinkeRE Non-Life.
VinkeRE runs the whole chain — vendor model outputs in, capital-aware decisions out. ELTs are forged once into seeded, reproducible YELTs; treaties are priced and structured with full drill-down by layer, event, peril and vendor model; portfolios accumulate gross and net of retrocession; capital is allocated at the point of underwriting.
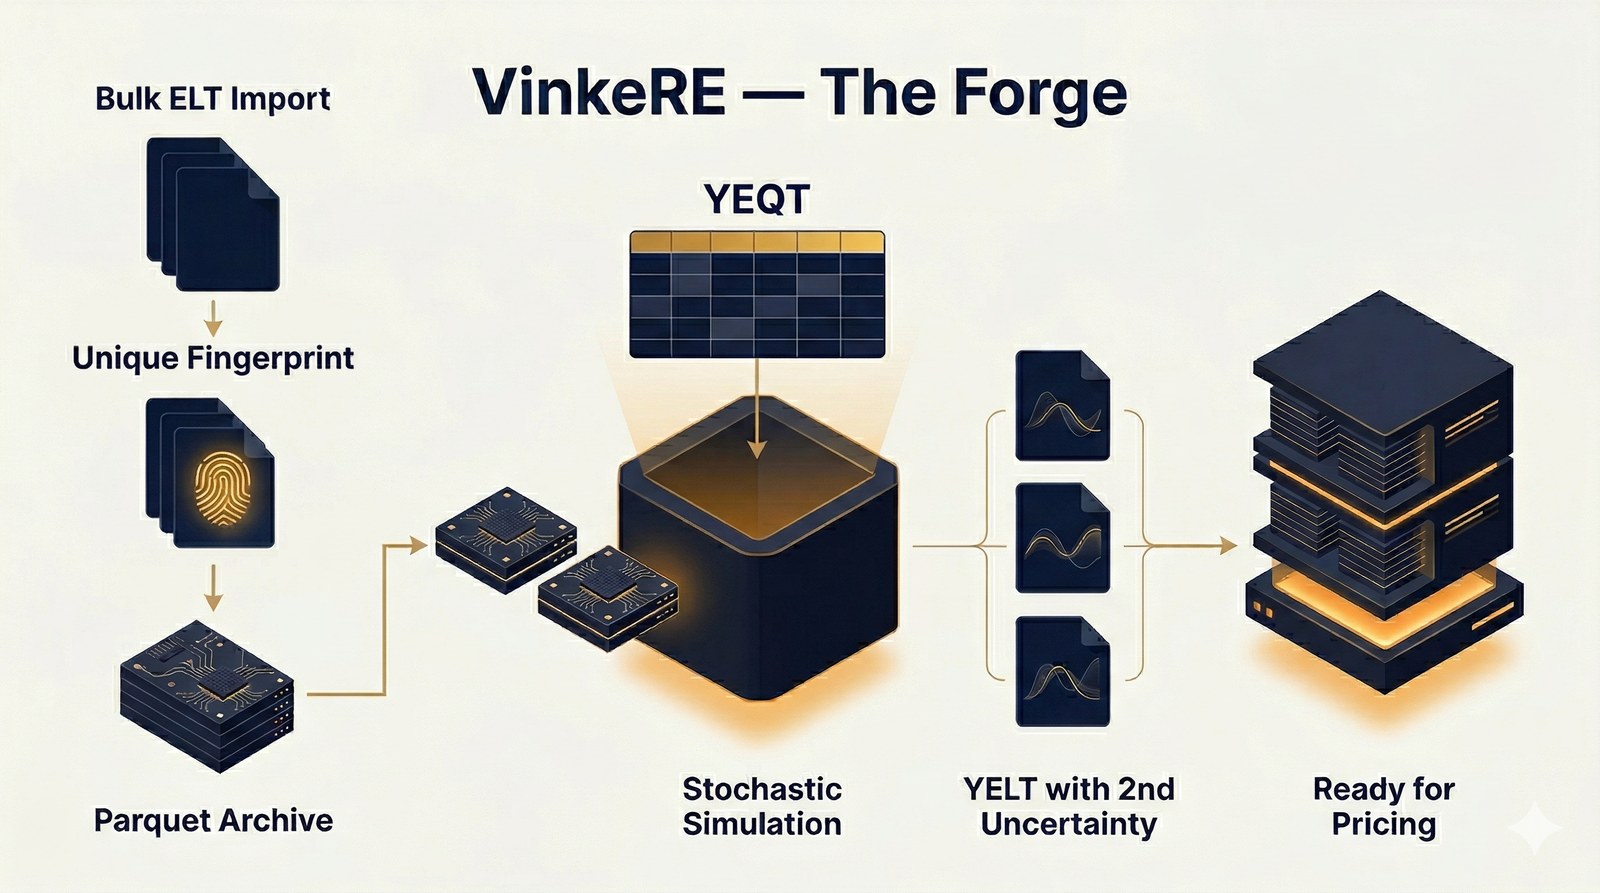
The Forge — where vendor model outputs become pricing-ready. Every ELT is fingerprinted once, archived in Parquet, and simulated into YELTs with proper secondary uncertainty via pre-simulated Year-Event Quantile Tables (YEQT) — seeded, stored, reproducible to the row.
Simulate once, price everywhere: no duplicate runs, no drift between analyses, a full audit trail by design.
Property Cat XL — 2026 Renewal
| Layer | Attach | Limit | EL % | Tech. Premium | RoL |
|---|---|---|---|---|---|
| Layer 1 | 10 | 15 | 9.8%→11.0%+12% | € 3.60M→€ 4.00M | 26.7% |
| Layer 2 | 25 | 25 | 5.6%→6.6%+17% | € 4.20M→€ 4.85M | 19.4% |
| Layer 3 | 50 | 25 | 3.2%→3.9%+22% | € 2.80M→€ 3.35M | 13.4% |
| Layer 4 | 75 | 50 | 1.6%→2.1%+30% | € 3.20M→€ 4.05M | 8.1% |
Property Cat XL — Capital Allocation
| Layer | Tech. Premium | Expected Loss | Expenses | Allocated SCR | Return on Capital |
|---|---|---|---|---|---|
| Layer 1 above hurdle | € 3.60M | € 1.47M | € 0.52M | € 8.5M | 18.9% |
| Layer 2 | € 4.20M | € 1.40M | € 0.61M | € 12.0M | 18.3% |
| Layer 3 | € 2.80M | € 0.80M | € 0.41M | € 11.5M | 13.8% |
| Layer 4 below hurdle | € 3.20M | € 0.80M | € 0.46M | € 17.5M | 11.1% |
Behind these screens, four capabilities — and one principle: everything traceable.
Cat Pricing
Complete workflow on vendor cat models (AIR, RMS). All reinsurance structures — XL with reinstatements, Quota Share, Stop Loss, Aggregate covers with annual deductibles, hybrid — with marginal impact analysis and roll-back per layer, event, peril and model.
Accumulation
Gross and net-of-retrocession accumulation with marginal contribution analysis. Full roll-back capability per layer, event ID, peril and vendor model. Full OEP and AEP curves, gross and net of retrocession.
Capital & Optimisation
Portfolio optimisation under solvency constraints. Share adjustment to optimise capital cost and return on equity — a direct link between pricing decisions and capital impact.
Reproducibility
Recipe system with a visual dependency graph for full traceability and instant replay. Change a source, an FX date or a catalogue — recompute in one click — only what changed. Every number auditable.
Under the hood · The Recipe graph
Price the treaty. The audit trail draws itself.
You never draw this graph — VinkeRE generates it with every analysis.
Every analysis in VinkeRE automatically produces a Recipe — the full record of its sources, adjustments and structure. The graph below is simply that Recipe made visible. And because the Recipe knows everything, repricing is trivial: update an FX date, apply an inflation scenario, or price the 2027 structure on 2026 YELTs — the engine replays the Recipe and recomputes only what changed. That is exactly what the scenario switches in the cockpit above are doing.
Architecture
Continuity & Trust
Full codebase held in secure escrow — guaranteeing continuity and complete source access under agreed conditions.
Client code review welcome. Model validation supported by full result convergence against the incumbent vendor engine, recipe traceability, and reproducible seeds stored with every YELT.
Licence & maintenance model — the engine evolves alongside your team, not instead of it.